
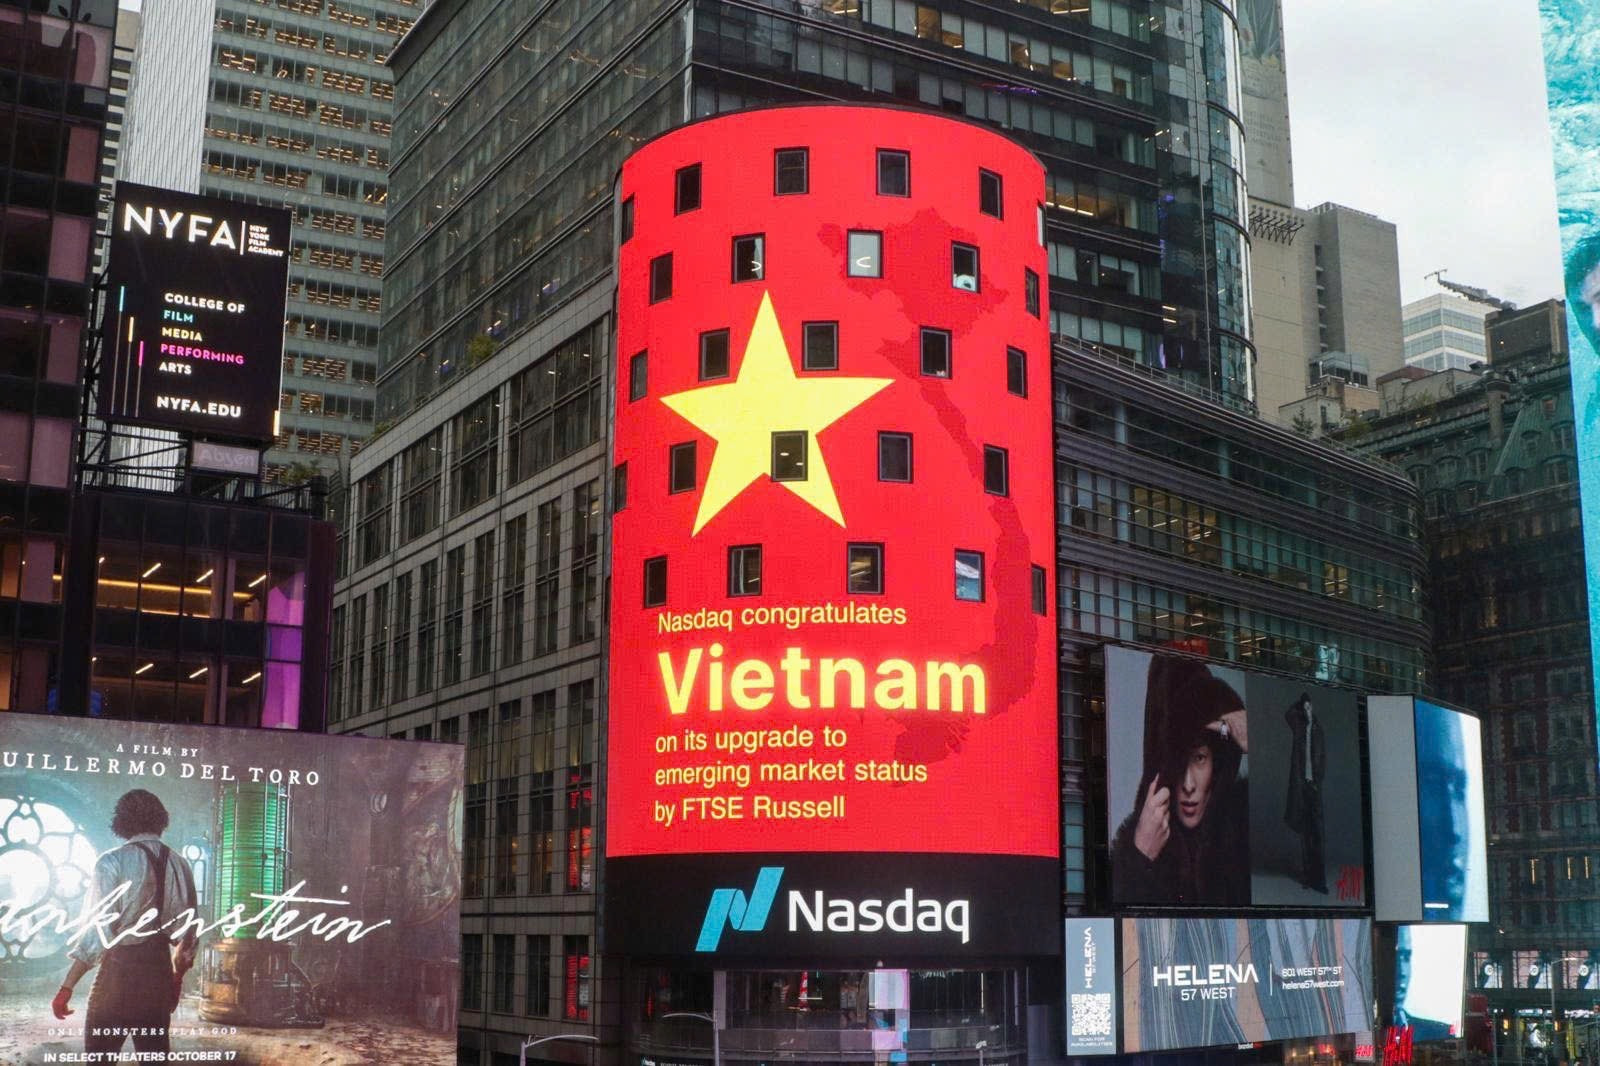
Vietnam’s emerging-market status puts its equities before a much larger pool of institutional investors, but FTSE Russell says market access, settlement efficiency and foreign-exchange infrastructure will determine whether capital stays.
MARKET INSIDER — Vietnam’s upgrade to Secondary Emerging Market status by FTSE Russell has placed its stock market on the radar of a substantially larger global institutional investor base, but attracting sustained foreign capital will require further reforms, a senior index executive said at the Vietnam Capital Market Forum 2026 in Ho Chi Minh City. Wanming Du, FTSE Russell’s Asia-Pacific director of index policy, said the reclassification creates opportunities for Vietnam to compete for investment from funds tracking emerging-market benchmarks, while warning that index inclusion alone does not guarantee long-term inflows.
Key takeaways
- FTSE Russell’s reclassification expands Vietnam’s visibility among international asset managers overseeing emerging-market investment portfolios.
- Global capital allocations will depend on market liquidity, corporate governance, transparency and operational accessibility, not simply index membership.
- FTSE Russell identified three priorities for further reform: easier market entry, more efficient trading and settlement, and improved foreign-exchange accessibility.
Why Does FTSE Russell’s Upgrade Matter for Vietnam?
Vietnam’s transition from Frontier Market to Secondary Emerging Market status represents a structural change in how its equity market is classified and assessed by international investors.
For years, Vietnam was categorized as a frontier market, placing it outside the core emerging-market universe followed by many large global investment institutions.
The upgrade changes that positioning.
At the Vietnam Capital Market Forum 2026, organized by Tuoi Tre newspaper in cooperation with the State Securities Commission of Vietnam, FTSE Russell’s Wanming Du said the country is now attracting attention from a significantly broader investment community.
That includes institutional investors whose portfolios are constructed around emerging-market equity benchmarks.
The distinction matters because index classification plays an important role in determining which markets international asset managers can consider, research and potentially include in their portfolios.
Passive investment funds seek to replicate benchmark composition, while active managers often use those benchmarks to define investment universes and measure performance.
Moving into the emerging-market category therefore increases Vietnam’s potential exposure to both groups.
However, Du emphasized that the significance of the upgrade extends beyond the immediate prospect of index-related capital inflows.
It changes the competitive environment in which Vietnam’s stock market operates.
Vietnamese equities will increasingly be evaluated alongside companies in established emerging markets, where investors expect high standards of disclosure, liquidity, governance and market infrastructure.
Will Vietnam’s Upgrade Trigger Billions in Foreign Investment?
The reclassification gives Vietnam access to a much larger potential investor audience, but the scale and timing of actual inflows remain uncertain.
FTSE Russell’s emerging-market index ecosystem is associated with investment portfolios representing substantial global assets.
However, those assets are not equivalent to capital committed to Vietnam.
Only a portion of benchmark-linked investment may ultimately be allocated to Vietnamese securities, depending on the country’s index weight, eligible constituents, implementation schedule and portfolio mandates.
Active investment managers also retain discretion over whether to invest.
Du cautioned that international investors do not make allocation decisions solely on the basis of a country’s market classification.
They evaluate macroeconomic prospects, trading liquidity, transparency, corporate governance and the efficiency of execution and settlement.
This distinction is particularly important for investors expecting the upgrade to produce an immediate and sustained stock-market rally.
Index inclusion can create demand for eligible securities, especially from passive funds, but it does not remove valuation risk or guarantee positive investment returns.
Foreign investors may also rebalance positions after implementation, while domestic market conditions can continue to influence share prices independently of benchmark changes.
The more important long-term question is whether Vietnam can convert its higher international profile into recurring portfolio allocations.
What Are the Three Reforms FTSE Russell Says Vietnam Still Needs?
Du identified three operational priorities that could determine how successfully Vietnam attracts and retains international capital.
Easier access for foreign institutional investors
The first priority is reducing the administrative and operational complexity of entering Vietnam’s securities market.
For a global asset manager, investing in a new country involves considerably more than selecting attractive stocks.
Institutions must establish trading accounts, appoint custodians, connect with brokers and comply with local regulatory and operational requirements.
These processes can affect how quickly an investment strategy is implemented and how efficiently a fund manages its exposure.
Du said simplifying account-opening procedures and improving coordination among market intermediaries would strengthen Vietnam’s attractiveness.
She also highlighted the importance of expanding access through established international financial institutions.
Such reforms could make Vietnam easier to integrate into the global investment infrastructure already used by large pension funds, asset managers and exchange-traded funds.
Reliable trading and settlement systems
The second priority is ensuring that trading and post-trade settlement operate consistently and predictably.
Vietnam has made progress in reducing pre-funding requirements for foreign institutional investors.
Previously, the requirement to have sufficient cash available before placing purchase orders created operational challenges for institutions accustomed to different settlement practices in developed and emerging markets.
Reforms allowing eligible foreign institutional investors to execute purchases without fully pre-funding their orders have addressed an important market-access concern.
Du welcomed these developments but emphasized that regulatory changes must translate into reliable day-to-day operations.
International investors need confidence that transactions can be executed and settled efficiently across different brokers, custodians and market participants.
Further improvements in technical infrastructure, connectivity with international brokers and settlement reliability would support that objective.
For passive funds in particular, predictable execution is essential when portfolios must be adjusted to reflect index changes.
Better foreign-exchange accessibility
The third priority is improving the practical ability of foreign investors to convert currencies and manage cross-border cash flows.
International equity investment involves more than buying and selling shares.
Funds must convert foreign currency into Vietnamese dong, manage settlement balances and repatriate investment proceeds or dividends.
The transparency, liquidity and efficiency of foreign-exchange transactions can therefore influence investment decisions.
Du said Vietnam should continue improving foreign-exchange accessibility while recognizing that emerging markets operate under different institutional and regulatory frameworks.
The objective is not necessarily to replicate the financial architecture of developed markets.
Instead, Vietnam needs arrangements that are sufficiently transparent, dependable and efficient for international institutional investors.
How Could the Upgrade Change Vietnam’s Stock Market?
The longer-term implications extend beyond the arrival of additional foreign investment.
Greater participation by global institutional investors could gradually influence liquidity, valuation practices, corporate disclosure and governance expectations.
Large international asset managers frequently evaluate companies using comparable financial metrics across markets, including earnings quality, return on equity, capital allocation and shareholder protections.
Vietnamese listed companies seeking sustained foreign investment may consequently face stronger incentives to improve investor relations, financial reporting and governance standards.
The upgrade could also increase differentiation between individual stocks.
Companies with sufficient free float, liquidity, transparency and foreign ownership accessibility may be better positioned to attract benchmark-related investment.
Other companies may benefit indirectly from broader market development but receive limited direct passive investment.
This means the reclassification should not be interpreted as a uniform positive catalyst for every listed company.
For domestic investors, the transition may increase the importance of institutional ownership trends, benchmark eligibility and international valuation comparisons.
It could also expose Vietnamese equities to shifts in global risk appetite, including changes in U.S. interest rates, the dollar and emerging-market fund flows.
Why It Matters for International Investors
Vietnam’s market upgrade represents an opportunity for global investors seeking exposure to one of Southeast Asia’s major manufacturing and export-oriented economies.
The country’s equity market offers access to sectors including banking, consumer businesses, property, industrials and technology-related activities.
However, international investors will need to distinguish between Vietnam’s long-term economic potential and the investability of individual listed securities.
Foreign ownership restrictions, trading liquidity, currency management and corporate governance can all affect portfolio construction.
For passive investors, benchmark eligibility and index implementation rules will be particularly important.
For active managers, the upgrade may expand the investment universe, but fundamental company analysis will remain central to allocation decisions.
The distinction between gaining international visibility and earning sustained international investment is therefore critical.
Vietnam has achieved a meaningful improvement in market classification. Maintaining investor confidence will require continued progress in the infrastructure and governance supporting that classification.
Outlook: What Investors Should Watch Next
Investors should monitor three developments as Vietnam consolidates its emerging-market position.
First, FTSE Russell’s subsequent index reviews, constituent eligibility assessments and implementation disclosures will help clarify how Vietnamese equities are represented in emerging-market benchmarks.
Second, regulators and market intermediaries will need to demonstrate that non-prefunding arrangements, trading connectivity and settlement procedures work reliably across a broad range of institutional investors.
Third, improvements in foreign-exchange accessibility, corporate disclosure and market liquidity will influence whether international funds expand their allocations beyond initial benchmark-related purchases.
For Vietnam, the upgrade is an important milestone rather than the completion of its capital-market reform agenda.
The central investment question is shifting from whether Vietnam qualifies as an emerging market to whether its market infrastructure, listed companies and regulatory environment can consistently meet the expectations of global institutional capital.
