
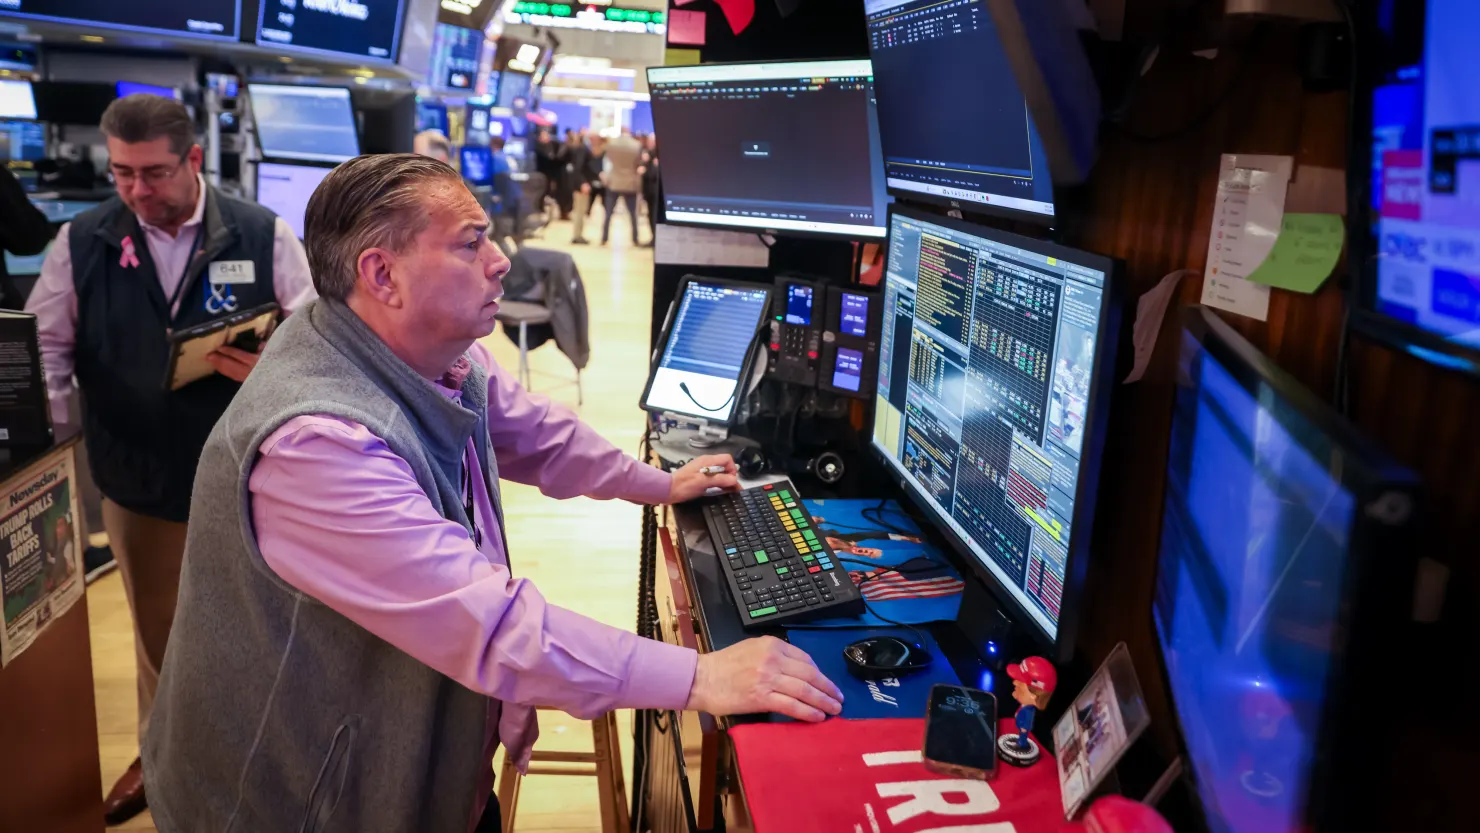
Wall Street faces further losses after Anthropic’s IPO fails to revive technology stocks, while Asian markets plunge and European chipmakers join the retreat.
MARKET INSIDER — U.S. stock futures declined on Friday, November 20, 2026, extending a global equity sell-off as investors questioned the valuations and investment returns underpinning the artificial intelligence boom. S&P 500 futures fell 0.57%, Nasdaq-100 futures dropped 1.08% and Dow Jones Industrial Average futures lost 0.23%. The weakness followed a volatile Wall Street session in which major indexes reversed early gains to close more than 2% lower, despite the highly anticipated market debut of Anthropic. Selling spread across Asia and Europe, with Japan’s Nikkei 225 and South Korea’s Kospi both falling more than 5%.
Key takeaways
- U.S. equities face their worst week in more than a year. The Dow has lost 6.2% so far this week, while the S&P 500 and Nasdaq have each declined approximately 5%.
- The AI sell-off has become global. Japan’s Nikkei 225 fell 5.06%, South Korea’s Kospi dropped 5.21%, and European technology shares declined 2.7% in early trading.
- Investors are reassessing risk. Deutsche Bank sees an oversold market, while JPMorgan expects demand for high-quality corporate bonds as equity volatility increases.
Wall Street’s Sharp Reversal Raises Questions About Market Confidence
U.S. stocks suffered another substantial decline Thursday as early optimism surrounding Anthropic’s initial public offering gave way to broad selling.
The Nasdaq Composite initially advanced as much as 2.1%, while the S&P 500 rose up to 1.3% ahead of the AI developer’s first trade.
However, the gains quickly evaporated as technology shares came under pressure.
By the close, all three major U.S. equity benchmarks had fallen more than 2%.
The Dow Jones Industrial Average finished below 50,000 for the first time since June, according to the supplied CNBC market report.
The reversal was particularly significant because it occurred during one of the most closely watched technology listings of the year.
Anthropic’s IPO had been expected to provide a fresh measure of investor appetite for companies developing advanced AI models.
Instead, the broader market decline highlighted concerns about stretched valuations, large capital expenditure commitments and the profitability of AI-related investments.
The timing of the reversal does not establish that Anthropic’s listing caused the sell-off. Investors were also responding to an accumulation of negative market catalysts and broader changes in risk appetite.
Nevertheless, the inability of a major AI listing to sustain market optimism suggests that investors have become increasingly selective about technology exposure.
Dow Heads for Worst Week Since April 2025
The sell-off has placed major U.S. equity indexes on course for their steepest weekly declines in more than a year.
Through Thursday, the Dow had fallen 6.2% for the week, putting it on track for its worst performance since April 2025.
The S&P 500 and Nasdaq Composite were each down approximately 5% over the same period.
The scale of the declines suggests that selling pressure has extended beyond a handful of expensive technology stocks.
A rotation away from AI-related companies has increasingly affected the broader equity market, including businesses with less direct exposure to artificial intelligence.
Such broadening can occur when investors reduce overall portfolio risk, rebalance positions or respond to losses in highly concentrated holdings.
The speed of the decline has also raised questions about whether market positioning has become excessively bearish.
Binky Chadha, a strategist at Deutsche Bank, told CNBC that the broader market appeared deeply oversold, even as economic growth and corporate earnings remained relatively strong.
He argued that the initial rotation out of technology had been compounded by additional negative catalysts, eventually spreading to the wider market.
An oversold market can experience sharp technical rebounds if selling pressure eases.
However, oversold conditions do not guarantee that prices have reached a bottom, particularly when investors are still adjusting earnings expectations or valuations.
Asian Markets Plunge as Semiconductor Stocks Lead Losses
Asian equity markets experienced some of Friday’s largest declines, underscoring the region’s exposure to the global technology investment cycle.
Japan’s Nikkei 225 dropped 5.06% to close at 56,436.65.
South Korea’s Kospi sank 5.21% to finish at 4,869.96.
Mainland China’s CSI 300 slipped 0.76% to 3,954.57, while Hong Kong’s Hang Seng Index was down 2.24% during its final hour of trading.
Australia’s S&P/ASX 200 closed at 8,592.6, although the supplied report did not specify its daily percentage change.
The particularly steep losses in Japan and South Korea reflect the importance of semiconductor manufacturers, electronics companies and technology-related investment in their equity markets.
Japanese companies supply critical equipment used in semiconductor fabrication, while South Korean manufacturers play a major role in producing memory chips for advanced computing systems.
These industries have benefited from expectations that AI developers and cloud infrastructure providers will continue expanding computing capacity.
However, the same exposure makes their shares sensitive to changes in forecasts for AI-related capital spending.
A slowdown in infrastructure investment, or even a reduction in expected growth rates, could influence semiconductor demand projections and investor valuations.
Friday’s market declines do not independently establish that AI customers have reduced their orders.
They do indicate that investors are assigning greater weight to the risks associated with the industry’s investment cycle.
European Technology Stocks Join the Global Retreat
The sell-off extended into Europe as regional markets opened lower Friday.
The benchmark Stoxx Europe 600 index declined 0.83% in early trading after reaching a four-week low on Thursday.
European technology shares fell approximately 2.7%, making the sector one of the weakest areas of the regional market.
Semiconductor equipment companies ASML, ASM International and BE Semiconductor Industries were among the notable decliners.
These businesses occupy important positions in the global chip manufacturing supply chain.
ASML supplies advanced lithography systems, while ASM International specializes in semiconductor processing equipment. BE Semiconductor Industries develops assembly and packaging technologies.
Their exposure to semiconductor manufacturers links their earnings outlook to investment in advanced production capacity.
If expectations for AI infrastructure spending weaken, investors may reassess the growth assumptions embedded in semiconductor equipment valuations.
However, equipment demand is also influenced by technological upgrades, manufacturing capacity requirements and investment cycles outside AI.
The European decline therefore reflects both global technology sentiment and concerns about future industry spending.
Is the AI Trade Becoming a Broader Market Risk?
The latest market turmoil illustrates how closely global equity performance has become linked to expectations for artificial intelligence.
Large technology companies, semiconductor manufacturers and computing infrastructure providers have attracted substantial investment based on anticipated demand for AI services.
The investment cycle has also extended into electricity generation, data-center construction, networking equipment and advanced manufacturing.
However, the financial returns on these investments remain uncertain.
AI developers face substantial expenses associated with model training, inference, computing capacity and technical personnel.
Cloud providers must balance infrastructure expansion against utilization rates and customer demand.
Semiconductor companies benefit from equipment orders but remain exposed to cyclical changes in spending.
Investors are increasingly asking whether the revenue generated by AI applications will justify the capital committed across the supply chain.
The distinction matters because strong long-term demand for AI technology does not necessarily mean every company involved will deliver attractive shareholder returns.
When expectations are elevated, even modest changes in growth assumptions can lead to significant valuation adjustments.
The current sell-off may therefore represent a reassessment of investment economics rather than a rejection of AI’s technological potential.
Why Investors Are Turning Toward Investment-Grade Bonds
As equity volatility increases, attention is shifting toward higher-quality fixed-income assets.
Matthias Reschke, JPMorgan’s head of European Investment Grade Finance, told CNBC that corporate credit spreads had remained relatively resilient despite the stock-market sell-off.
He acknowledged that market participants had become more nervous and that spreads were widening, including among investment-grade issuers.
However, he suggested that highly rated corporate bonds could attract investors seeking to reduce risk.
Investment-grade bonds are issued by companies assessed as having comparatively strong creditworthiness.
They generally offer lower yields than high-yield corporate debt but carry lower expected default risk.
In periods of equity-market volatility, investors may prefer the more predictable contractual income associated with high-quality bonds.
Nevertheless, investment-grade debt is not risk-free.
Bond prices remain sensitive to changes in government yields, credit spreads and issuer-specific financial conditions.
Reschke also highlighted persistent inflation as an important concern.
If inflation remains elevated, benchmark 10-year government bond yields could stay high, limiting the scope for bond-price appreciation even as demand for defensive assets increases.
For institutional investors, the decision is therefore not simply whether to move from equities into bonds, but how to balance credit quality, duration and interest-rate risk.
Why It Matters for Asian and Emerging Markets
The global sell-off has important implications for economies connected to technology manufacturing and international capital markets.
Japan, South Korea and Taiwan are deeply integrated into semiconductor and advanced electronics supply chains.
Changes in AI investment expectations can therefore affect both their equity markets and perceptions of future industrial demand.
For Vietnam, the direct impact is likely to operate through investor sentiment, foreign capital flows and expectations for electronics manufacturing.
Vietnam’s role in regional manufacturing supply chains makes global technology spending relevant to export-oriented businesses and future investment decisions.
A prolonged correction in global equities could also increase risk aversion toward emerging markets, particularly if international investors reduce exposure to volatile assets.
At the same time, lower equity valuations may create opportunities for investors with longer investment horizons.
Whether those opportunities are attractive will depend on company earnings, balance-sheet strength and the extent to which valuations have adjusted to realistic growth expectations.
Outlook: Can Markets Stabilize?
Investors will focus on several near-term indicators to assess whether the sell-off is approaching exhaustion.
The University of Michigan’s final November consumer sentiment reading is scheduled for Friday and could provide insight into U.S. household confidence and inflation expectations.
BJ’s Wholesale Club is also expected to report earnings before the U.S. market opens.
Beyond the day’s economic calendar, investors will watch technology-sector earnings guidance, AI capital expenditure commitments and credit-market conditions.
A stabilization in semiconductor shares and narrower corporate credit spreads could indicate that risk appetite is recovering.
Conversely, continued selling across technology, industrial and financial stocks would suggest that the correction is becoming more deeply embedded in the broader market.
Deutsche Bank’s assessment that equities are oversold offers one possible basis for a rebound, but the durability of any recovery will depend on fundamentals.
For now, the combination of falling U.S. futures, steep Asian losses and weakness in European technology stocks indicates that global investors remain cautious about the valuations and financial returns underpinning the AI investment boom.
