
The U.S. 10-year yield slips below 5%, but investors face continued uncertainty over inflation and further Fed hikes.
MARKET INSIDER — U.S. Treasury yields declined on Monday, September 21, as falling oil prices eased inflation concerns and supported a broader recovery in government bonds and equities.
The benchmark 10-year yield fell about 3 basis points to 4.967% in early trading, retreating from last week’s 19-year high of 5.041%. European government bond yields also moved lower.
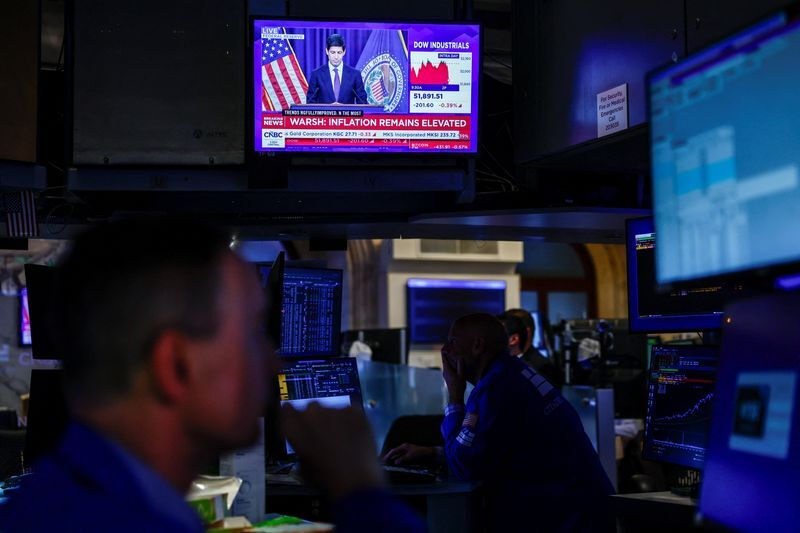
The pullback offered modest relief after the Federal Reserve raised interest rates last week. However, borrowing costs remain elevated, and the durability of the bond-market recovery will depend on energy supplies, incoming economic data and signals about further monetary tightening.
Key Highlights
- The U.S. 10-year Treasury yield eased to 4.967%, while the 30-year yield remained above 5.3%.
- Lower oil prices helped lift bonds and stocks, although Middle East hostilities continued.
- Business surveys, jobless claims and Federal Reserve speeches will help shape expectations for the next policy move.
Bonds recover after last week’s selloff
The two-year Treasury yield, which is particularly sensitive to expectations for Federal Reserve policy, slipped approximately 1 basis point to 4.729%. The 30-year yield fell about 3 basis points to 5.306%.
Bond prices rise when yields fall. One basis point equals 0.01 percentage point.
Monday’s early 10-year reading was roughly 7.4 basis points below last week’s peak. That represents a limited retreat from recent highs rather than a substantial reversal in financing conditions.
Separate market reporting also placed the benchmark yield near 4.97% during European trading as crude prices declined, according to Barron’s market update
In Europe, German 10-year Bund and U.K. gilt yields each fell around 5 basis points. Japanese markets were closed for a holiday, leaving trading without an important source of regional price signals.
Why cheaper oil supports both bonds and stocks
Lower energy prices can benefit financial markets through several channels.
For bonds, cheaper oil can reduce concern about future inflation and the interest-rate increases needed to contain it. For businesses and households, it can ease transport, production and consumption costs.
The simultaneous improvement in bonds and equities is consistent with relief over inflation and supply risks. A bond rally driven mainly by deteriorating growth expectations would carry a less encouraging message for corporate earnings.
That distinction remains important because Middle East hostilities have continued. This week’s United Nations General Assembly provides a setting for diplomatic engagement, while Washington is pressing Tehran for an agreement that would restore trade flows through the Strait of Hormuz.
Any lasting improvement in energy-market conditions will require evidence of more dependable supplies and shipping access.
The Fed’s tightening outlook remains unresolved
Investors are still assessing the implications of the Federal Reserve’s quarter-percentage-point rate increase last week and whether additional hikes will follow before year-end.
The European Central Bank also raised rates this month, while the Bank of England held its policy rate unchanged at its latest meeting.
Falling market yields do not mean central banks have changed course. Longer-term bond yields reflect expectations for future policy rates, inflation and the compensation investors demand for holding debt over time.
A decline in oil prices can improve that calculation without removing underlying price pressures elsewhere in the economy.
The relatively small move in the two-year Treasury yield suggests Monday’s early trading had not produced a dramatic reassessment of the near-term U.S. policy outlook.
Implications for Asia and emerging markets
For Asian economies that import energy, sustained declines in oil prices could ease import bills and pressure on business margins.
Lower U.S. Treasury yields could also help borrowers issuing dollar-denominated debt. Their actual financing costs, however, depend on credit spreads—the additional yield investors require above U.S. government bonds—as well as currency movements.
This means a Treasury rally does not guarantee cheaper funding for every emerging-market borrower. A stronger dollar or widening credit spreads could offset the benefit.
For equities, lower yields can support valuations by reducing the rate used to discount future earnings. But companies still need to deliver profits: a small decline from unusually high bond yields does not eliminate financing pressure.
What investors should watch this week
The calendar includes S&P Global purchasing managers’ indexes on Wednesday, September 23, followed by U.S. initial jobless claims on Thursday, September 24.
The business surveys should provide fresh indications of activity, employment and price pressures. Jobless claims will help investors assess whether tighter financial conditions are affecting the labor market.
Remarks from New York Fed President John Williams, Richmond Fed President Tom Barkin and other policymakers will also be closely watched for guidance on inflation and the pace of further tightening.
The central test is whether easing energy costs persist alongside resilient growth. That combination could support both bonds and equities; renewed supply disruption would threaten Monday’s relief.
